MSc thesis · 2024–Dec 2026
Robust cluster analysis of financial returns
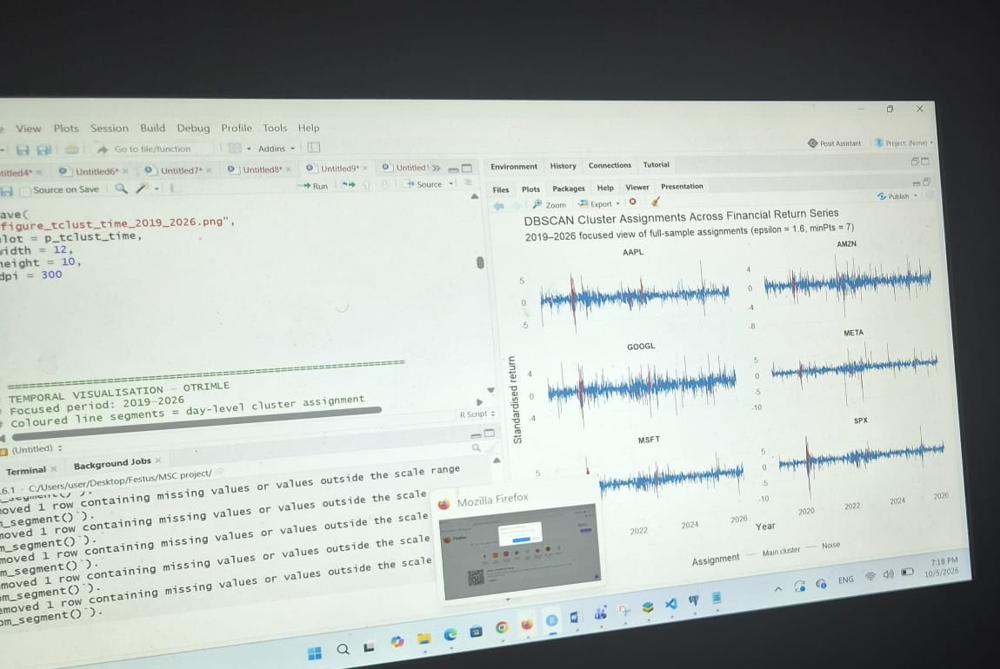
I compare GMM, TCLUST, OTRIMLE and DBSCAN on 3,502 daily log returns for Apple, Microsoft, Google, Meta, Amazon and the S&P 500, choosing models with a sequential parametric bootstrap (B = 999). The outliers line up with the VIX around COVID-19, the Fed hikes and the 2025 tariff shocks.
The methods agree on the extreme days but not on the structure inside the clusters, and that agreement weakens at k = 4.
Rtclustotrimledbscanmclustbootstrap
Supervised by Prof. Christian Hennig and Dr. Laura Anderlucci
Code, figures and data on GitHub ↗